Practice Set 4.2 Algebra 10th Std Maths Part 1 Answers Chapter 4 Financial Planning
Question 1
Maharashtra Board Solution
‘Chetana Store’ paid total GST of ₹ 1,00,500 at the time of purchase and collected GST ₹ 1,22,500 at the time of sale during 1st of July 2017 to 31st July 2017. Find the GST payable by Chetana Stores.
Solution & Step-by-Step Answer:
Output tax (Tax collected at the time of sale) = ₹ 1,22,500 Input tax (Tax paid at the time of purchase) = ₹ 1,00,500 ITC (Input Tax credit) = ₹ 1,00,500. GST payable = Output tax – ITC = 1,22,500 – 1,00,500 = ₹ 22,000 GST payable by Chetana stores is ₹ 22,000.
Question 2
Maharashtra Board Solution
Nazama is a proprietor of a firm, registered under GST. She has paid GST of ₹ 12,500 on purchase and collected ₹ 14,750 on sale. What is the amount of ITC to be claimed? What is the amount of GST payable?
Solution & Step-by-Step Answer:
Output tax = ₹ 14,750 Input tax = ₹ 12,500 ∴ ITC for Nazama = ₹ 12,500. ∴ GST payable = Output tax – ITC = 14750 – 12500 = ₹ 2250 ∴ Amount of ITC to be claimed is ₹ 12,500 and amount of GST payable is ₹ 2250.
Question 3
Maharashtra Board Solution
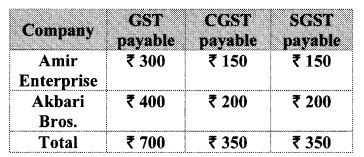
Amir Enterprise purchased chocolate sauce bottles and paid GST of ₹ 3800. He sold those bottles to Akbari Bros, and collected GST of ₹ 4100. Mayank Food Corner purchased these bottles from Akbari Bros, and paid GST of ₹ 4500. Find the amount of GST payable at every stage of trading and hence find payable CGST and SGST.
Solution & Step-by-Step Answer:
For Amir Enterprise: Output tax = ₹ 4100 Input tax = ₹ 3800 ITC for Amir enterprise = ₹ 3800. ∴ GST payable = Output tax – ITC = 4100 – 3800 = ₹ 300 For Akbari Bros.: Output tax = ₹ 4500 Input tax = ₹ 4100 ITC for Akbari Bros = ₹ 4100. GST payable = Output tax – ITC = 4500 – 4100 = ₹ 400 ∴ Statement of GST payable at every stage of trading:
Question 4
Maharashtra Board Solution
Malik Gas Agency (Chandigarh Union Territory) purchased some gas cylinders for industrial use for ₹ 24,500, and sold them to the local customers for ₹ 26,500. Find the GST to be paid at the rate of 5% and hence the CGST and UTGST to be paid for this transaction, (for Union Territories there is UTGST instead of SGST.)
Solution & Step-by-Step Answer:
For Malik Gas Agency: Output tax = 5% of 26500 = × 26500 = ₹ 1325 Input tax = 5% of 24500 = × 24500 = ₹ 1225 ITC for Malik Gas Agency = ₹ 1225. ∴ GST payable = Output tax – ITC = 1325 – 1225 = ₹ 100 ∴ CGST = UTGST = ₹ 50 ∴ The GST to be paid at the rate of 5% is ₹ 100 and hence, CGST and UTGST paid for the transaction is ₹ 50 each.
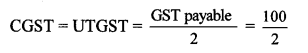
Question 5
Maharashtra Board Solution
M/s Beauty Products paid 18% GST on cosmetics worth ₹ 6000 and sold to a customer for ₹ 10,000. What are the amounts of CGST and SGST shown in the tax invoice issued?
Solution & Step-by-Step Answer:
Output tax = 18% of 10,000 = × 10,000 = ₹ 1800 ∴ Amount of CGST and SGST shown in the tax invoice issued is ₹ 900 each.
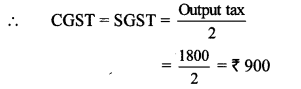
Question 6
Maharashtra Board Solution
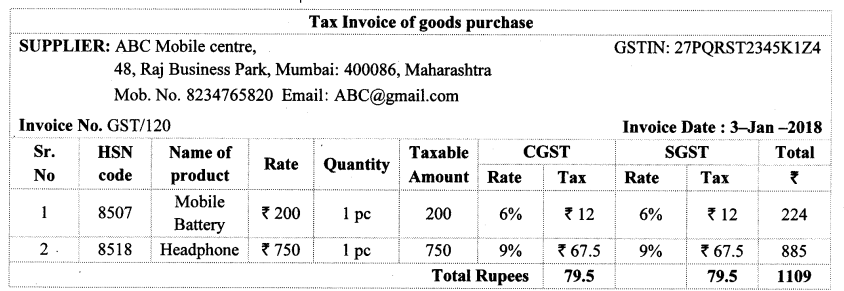
Prepare Business to Consumer (B2C) tax invoice using given information. Write the name of the supplier, address, state, Date, Invoice number, GSTIN etc. as per your choice. Supplier: M/s ______ Address _______ State _______ Date _______ Invoice No. _______ GSTIN _______ Particulars Rate of Mobile Battery ₹ 200 Rate of GST 12% HSN 8507 1 PC Rate of Headphone ₹750 Rate of GST 18% HSN 8518 1 Pc
Solution & Step-by-Step Answer:
Rate of Mobile Battery = ₹200 CGST = 6% of 200 = × 200 = ₹ 12 ∴ CGST = SGST = ₹ 12
Rate of Headphone = ₹ 750
COST = 9% of 750
= × 750
= ₹ 67.5
∴ CGST = SGST = ₹ 67.5
Question 7
Maharashtra Board Solution
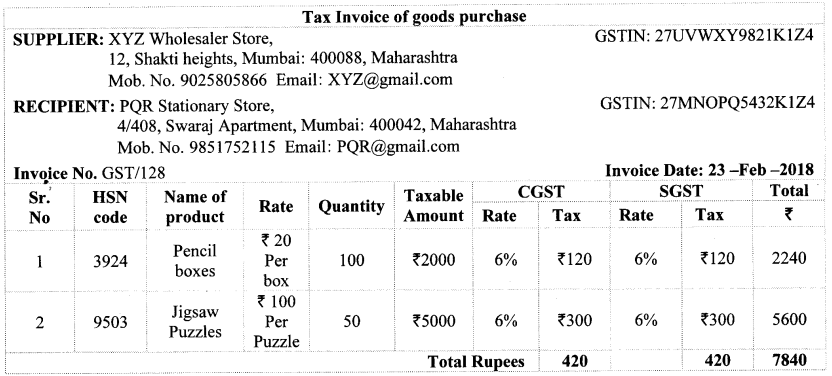
Prepare Business to Business (B2B) Tax Invoice as per the details given below, name of the supplier, address, Date etc. as per your choice. Supplier – Name, Address, State, GSTIN, Invoice No., Date Recipient – Name, Address, State, GSTIN, Items: i. Pencil boxes 100, HSN – 3924, Rate – ₹ 20, GST 12% ii. Jigsaw Puzzles 50, HSN 9503, Rate – ₹ 100 GST 12%.
Solution & Step-by-Step Answer:
Cost of 100 Pencil boxes = 20 × 1oo = ₹ 2000 CGST = 6% of 2000 = × 2000 = ₹ 120 ∴ CGST = SGST = ₹ 120
Cost of 50 Jigsaw Puzzles = 100 × 50
= ₹ 5000
CGST = 6% of 5000
= × 5000
= ₹ 300
CGST – SGST = ₹ 300
Question 1
Maharashtra Board Solution
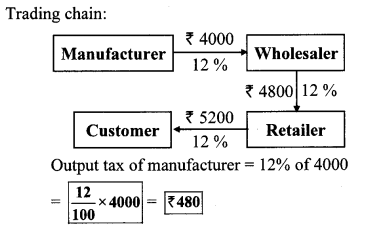
Suppose a manufacturer sold a cycle for a taxable value of ₹ 4000 to the wholesaler. Wholesaler sold it to the retailer for ₹ 4800 (taxable value). Retailer sold it to a customer for ₹ 5200 (taxable value). Rate of GST is 12%. Complete the following activity to find the payable CGST and SGST at each stage of trading. (Textbook pg. no. 92)
Solution & Step-by-Step Answer:
GST payable by manufacturer = ₹ 480 Output tax of wholesaler = 12% of 4800 = × 4800 = ₹ 576 ∴ GST payable by wholesaler = Output tax – Input tax = 576 – 480 = ₹ 96 Output tax of retailer = 12% of 5200
Question 2
Maharashtra Board Solution
Suppose in the month of July the output tax of a trader is equal to the input tax, then what is his payable GST?(Textbook pg. no. 93)
Solution & Step-by-Step Answer:
Here, output tax is same as input tax. ∴ Trader payable GST will be zero.
Question 3
Maharashtra Board Solution
Suppose in the month of July output tax of a trader is less than the input tax then how to compute his GST? (Textbook pg. no. 93)
Solution & Step-by-Step Answer:
If output tax of a trader in a particular month is less than his input tax, then he won’t be able to get entire credit for his input tax. In such a case his balance credit will be carried forward and adjusted against the subsequent transactions.